How Is Cryptocurrency Taxed? A Plain-English Guide
By Emily Carter
Policy Correspondent · June 13, 2026 · 9 min read
Published June 13, 2026 · Reviewed to our editorial standards. This article is informational and not financial advice.
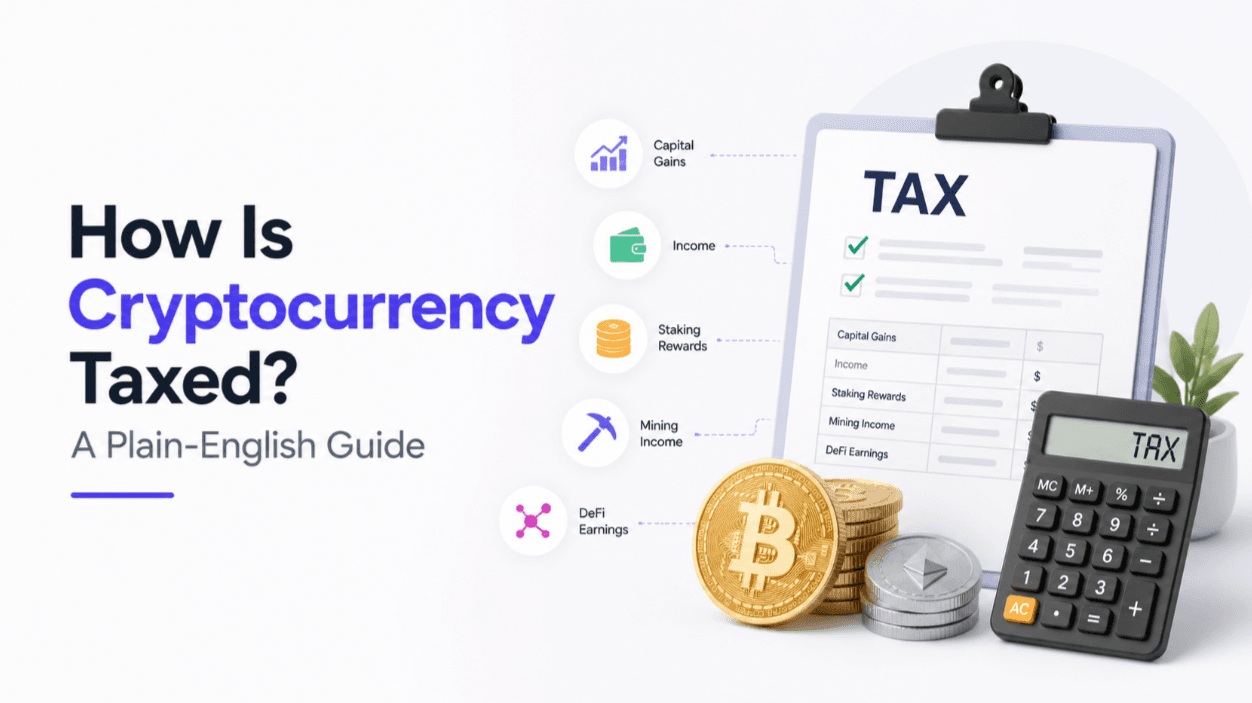
In most major economies, cryptocurrency is taxed as property rather than as money, which means selling, swapping or spending it can produce a taxable capital gain or loss. Separately, receiving crypto as payment, staking rewards or mining proceeds is usually treated as income at its value when received. The exact rates, thresholds and forms differ by country and change often.
Key takeaways
- Many jurisdictions tax crypto as property, so a disposal is a taxable event.
- Buying and holding alone is generally not taxed; selling, swapping or spending usually is.
- Staking, mining, airdrops and crypto pay are commonly taxed as income on receipt.
- Your cost basis and holding period determine the gain and sometimes the rate.
- Accurate records of dates, amounts and values are the foundation of any filing.
Why crypto is usually taxed as property
Because tax codes predate digital assets, regulators have slotted crypto into existing categories rather than writing wholly new ones. The common landing spot is property or a capital asset, the same bucket used for shares and other investments. Under that treatment, you owe tax on the change in value between the moment you acquired a coin and the moment you disposed of it.
A handful of jurisdictions take a different path. Some treat long-held private holdings as tax-free after a waiting period, while others apply a flat rate to crypto gains or fold them into general income. The property model is the most widespread, but you should always confirm how your own tax authority classifies digital assets.
Taxable events versus non-taxable events
The single most useful habit is learning to spot a taxable event. A disposal happens whenever you part with a coin in a way that realises its value, even if no traditional currency changes hands.
Commonly taxable
- Selling crypto for fiat currency such as dollars or euros.
- Swapping one token for another, including stablecoins.
- Spending crypto on goods or services.
- Earning staking, lending, mining or liquidity rewards.
- Receiving an airdrop or crypto wages, typically as income.
Usually not taxable
- Buying crypto with fiat and simply holding it.
- Moving coins between wallets you control.
- Donating to a registered charity, in many jurisdictions.
- Gifting within local exemption limits, where they exist.
Two further wrinkles trip people up. First, paying a network or platform fee in crypto can itself be a small disposal of the coins used to pay it. Second, a transfer that merely moves your own assets between wallets you control is generally not a disposal, even though it looks like activity on the blockchain. Learning to separate genuine disposals from cosmetic movement saves a great deal of confusion at filing time.
Capital gains and cost basis
A capital gain is the difference between what you received on disposal and your cost basis, which is generally what you paid plus associated fees. If you sell for less than your basis, the result is a capital loss, which many systems let you offset against other gains. Holding period often matters too: several jurisdictions tax assets held beyond a year at a lower long-term rate.
Tracking basis becomes tricky once you have bought the same coin at many prices. Tax authorities specify or permit particular accounting methods, such as first-in-first-out or specific identification, and the method you use can materially change your reported gain. Pick an approved method and apply it consistently.
Losses deserve as much attention as gains. Where a jurisdiction allows it, realising a loss can reduce the tax due on other gains, and some systems let unused losses carry forward to future years. Rules vary on whether losses from crypto can offset gains from other asset classes, and on whether quickly rebuying the same asset restricts the deduction, so the detail matters before you rely on a loss to lower a bill.
A simple worked example
Suppose you buy one unit of a token for the equivalent of 1,000 in your home currency, including fees, giving a cost basis of 1,000. A year later you swap it for another token when the first is worth 1,600. Even though you never touched cash, most property-based systems treat this as a disposal with a 600 gain. The second token now carries a fresh basis of 1,600 for the next time you dispose of it.
Income from staking, mining and rewards
When crypto lands in your wallet as a reward rather than a purchase, the value at receipt is frequently treated as ordinary income. That same value then becomes your cost basis, so a later sale can trigger a second, separate capital gains calculation on any further price movement. Mining and staking carried out as a business may face different rules and additional reporting.
Airdrops, hard forks and referral rewards often follow the same logic, though the timing of when income is recognised can be contested. Some jurisdictions tax these when you gain control of the assets; others wait until you can actually sell or use them. Decentralised-finance activity adds further complexity, because a single strategy can generate income, disposals and fee events in quick succession.
DeFi, NFTs and harder cases
Decentralised finance and collectibles stretch tax rules that were written with simpler transactions in mind. Lending, providing liquidity, wrapping tokens and claiming rewards can each be a separate event, and authorities have not always issued clear guidance on every variation. Non-fungible tokens are usually treated as property too, but some jurisdictions apply special rules to collectibles or to assets created by the seller.
- Providing liquidity may be treated as a disposal when you deposit or withdraw assets.
- Wrapping or bridging a token can count as a swap in some interpretations.
- NFT sales are commonly taxed as property disposals, with creator income taxed separately.
- Where guidance is unclear, a defensible, consistent position matters more than certainty.
The mistake we see most often is not under-reporting on purpose, but failing to keep records detailed enough to prove a basis years later. — CryptoCoinBeat analysis
Record-keeping and reporting
Good records turn a stressful filing into a routine one. For every transaction, aim to capture the date, the asset, the amount, the value in your home currency at the time, the counterparty or platform, and any fees. Many holders use dedicated tax software that imports exchange and wallet history, though the output still needs a careful human review.
- Export full transaction histories from each exchange and wallet you use.
- Record fiat values at the time of each event, not just at year-end.
- Keep evidence of cost basis for assets you may sell years later.
- Note the accounting method you chose and use it consistently.
- Retain records for as long as your jurisdiction requires after filing.
Cross-border and changing rules
Tax residency, not citizenship, usually decides where you owe crypto tax, and some people are liable in more than one place. International reporting frameworks are tightening, with exchanges increasingly sharing user data across borders. Treat any assumption that crypto activity is invisible to tax authorities as outdated.
This article is educational only and is not legal or tax advice. Crypto tax rules differ significantly by jurisdiction and change frequently, sometimes with retroactive effect. Before filing or making decisions with tax consequences, consult a qualified tax professional licensed in your country.
Spending crypto with a card is usually a disposal
Crypto cards have made this the most common accidental tax event. In most jurisdictions, spending a volatile asset is a disposal: the coffee is not the taxable event, converting bitcoin to pay for it is. Someone using a card daily can generate hundreds of small disposals in a year, each requiring a cost basis and a gain or loss.
Two things reduce that burden. Spending a stablecoin balance rather than a volatile asset produces gains close to zero, so the paperwork shrinks even where the disposal still technically occurs. And some cards offer a credit mode that borrows against collateral rather than selling it — in many jurisdictions a loan is not a disposal, which changes the position entirely. Our best crypto cards table records which cards offer which model.
Whichever route you take, export the card's transaction history monthly rather than annually. Reconstructing a year of small disposals from statements is the single most tedious job in crypto tax, and it is entirely avoidable.
This is general information, not advice
Rules differ by country and change between tax years, and the treatment of staking rewards, airdrops and card spending is among the least settled areas. Use this to know which questions to ask, and confirm the answers with a professional in your jurisdiction before filing.
Frequently asked questions
Do I owe tax if I only buy and hold crypto?+
In most jurisdictions, buying crypto with regular currency and holding it does not create a taxable event on its own. Tax usually arises only when you dispose of the asset by selling, swapping or spending it, or when you receive crypto as income such as staking rewards.
Is swapping one coin for another taxable?+
Generally yes. Most tax authorities treat a token-to-token swap as a disposal of the first asset, so any gain or loss measured against its cost basis becomes reportable. This applies even when no traditional currency is involved, including swaps into stablecoins, in many countries.
How are staking and mining rewards taxed?+
Rewards are commonly taxed as income at their market value when you receive them. That value then becomes the cost basis for the new coins, so a later sale can trigger a separate capital gains calculation on any additional price change between receipt and disposal.
What records should I keep for crypto taxes?+
Keep the date, asset, amount, home-currency value, platform and fees for every transaction, plus proof of your cost basis. Export histories from each exchange and wallet, and retain them for the period your tax authority requires after filing, which is often several years.
Written by
Emily CarterFormer regulatory analyst · J.D.
Emily Carter is a legal and regulatory writer specializing in cryptocurrency, blockchain policy, and digital asset compliance. Before joining CRYPTO·COINBEAT, she worked as a regulatory analyst in the United States, tracking developments in federal financial legislation, anti-money laundering (AML) requirements, and emerging policies shaping the digital asset industry. She earned her Juris Doctor (J.D.) degree and combines legal expertise with a talent for translating complex regulatory topics into clear, accessible language. Her work focuses on cryptocurrency taxation, DeFi regulation, exchange compliance, stablecoins, and the evolving role of U.S. agencies in overseeing digital assets. At CRYPTO·COINBEAT, Emily writes educational guides and policy explainers designed for both newcomers and experienced crypto users. She is committed to helping readers understand how regulatory changes affect investors, businesses, and the broader blockchain ecosystem.
Keep Reading
KYC and AML in Crypto Explained
KYC verifies who you are; AML is the broader effort to stop illicit money moving through crypto. Together they shape how regulated platforms operate.
Emily Carter · April 27, 2026→
Is Cryptocurrency Legal? A Country-by-Country Guide
Cryptocurrency is legal to own and trade in most countries, restricted in some, and banned in a few. Status depends on local law and changes over time.
Maria Fernandez · May 9, 2026→
What Is MiCA? The EU Crypto Regulation Explained
MiCA is the European Union's dedicated framework for crypto-assets, creating one set of rules across member states for issuers, stablecoins and service providers.
Emily Carter · May 23, 2026→